

Picture the worst kind of “no.” A customer is standing at your counter, wallet open, ready to buy — and your only way to take money is a cash jar and a hopeful smile. They shrug, say they’ll come back, and walk out the door. That sale is gone, and so is the trust that you’re a business that has its act together.
The right credit card reader for small business owners closes that gap. It turns a maybe into a paid-in-full, whether you’re behind a register, parked at a farmers market, or standing in someone’s driveway writing up an estimate. The problem is that “card reader” now covers everything from a $49 dongle to a full smart terminal, and the wrong choice can quietly cost you thousands in junk fees and slow deposits. This guide breaks down the real differences so you can pick with confidence.
Why the Right Credit Card Reader for Small Business Matters
Cash is no longer king. According to the Federal Reserve’s Diary of Consumer Payment Choice, cash was used for only about 14% of all payments in 2024, down from roughly a third a decade earlier. When most of your customers reach for a card or a phone, the machine on your counter isn’t a “nice to have” — it’s the difference between capturing a sale and losing it.
A good credit card reader for small business does three things at once. It gets you paid faster, since card transactions settle far quicker than chasing an invoice. It makes you look established, because a smooth tap-and-go checkout signals that you’re a real, trustworthy operation. And it hands you data — sales trends, best-selling items, busiest hours — that a cash box never could. The reader is small, but the ripple effect on your bottom line is not.
Here’s the catch that trips up a lot of owners: the hardware is only half the story. Two identical-looking terminals can carry wildly different processing rates, contract terms, and funding speeds behind the scenes. That’s why choosing a reader is really about choosing the partner and the pricing behind it, not just the plastic on the counter.
The Main Types of Card Readers (and Who Each One Fits)
There’s no single “best” device — there’s the best one for how you actually sell. Most options fall into four buckets. If you want to compare full lineups side by side, the POS devices overview is a good place to start.

Mobile and handheld readers
These are the pocket-sized champions. A compact reader pairs with your phone or works on its own over Wi-Fi and cellular, so you can take a tap or a chip payment anywhere. They’re ideal for food trucks, mobile groomers, market vendors, contractors, and pop-up shops. Something like the Clover Go fits in an apron pocket yet still accepts contactless, chip, and digital wallets. If you sell on the move, this is often the smartest starting point — and it pairs naturally with a broader mobile payment processing setup.
All-in-one smart handhelds
A step up from a basic dongle, these are full computers you can hold in one hand. They print receipts, manage inventory, run tabs, and take every payment type without needing a phone. The Clover Flex is the classic example: line-busting at a busy retail counter, tableside ordering at a restaurant, or on-site invoicing at a job. If you want mobility and muscle, this is the sweet spot.
Countertop terminals
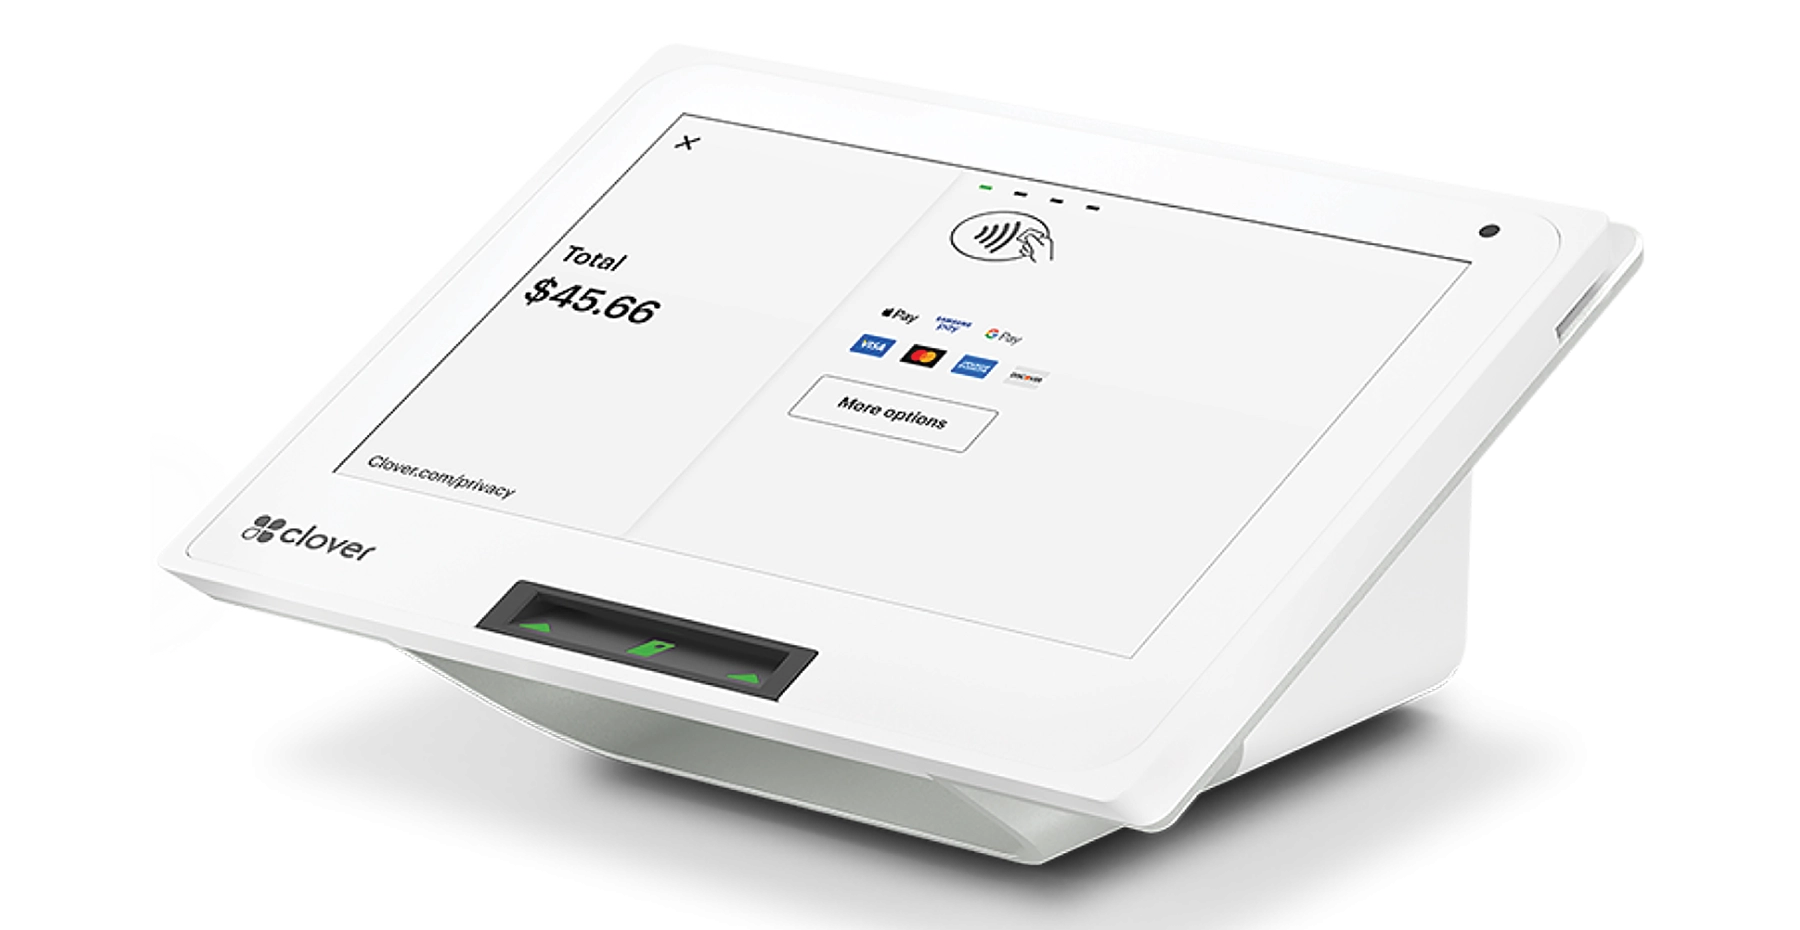
When you have a fixed checkout, a countertop unit gives you a bigger screen, a customer-facing display, and rock-solid reliability. The Clover Mini anchors a retail counter or a coffee bar beautifully — it’s compact enough to save space but powerful enough to run your whole front end. This is the workhorse for shops, salons, and quick-service spots that ring people up in one spot all day.
Keyed and virtual readers
Not every payment happens face to face. If you invoice clients, take orders over the phone, or run a service business, a virtual terminal lets you key in card details from any browser — no physical device required. Many owners run a virtual terminal alongside a physical reader so no sale slips through the cracks, whether the customer is standing in front of them or calling from across town.
What to Look For Before You Buy
The device is easy to fall in love with. The fine print is where deals are won or lost. Before you commit to any credit card reader for small business use, run through this checklist.
Transparent pricing. Watch for tiered rates that bury your true cost. Ask for a clear breakdown and compare it honestly — a difference of a few tenths of a percent adds up fast at volume. You can also look at whether a Zero Fee Processing program fits your business, which offsets processing costs so more of each sale stays in your pocket.
Security and PCI compliance. Your reader has to protect card data, full stop. Look for end-to-end encryption and tokenization, and make sure your provider helps you meet the standards set by the PCI Security Standards Council. A breach isn’t just a headache; it can carry fines that dwarf any hardware savings.
Funding speed. How fast does the money hit your account? Next-day or same-day funding keeps your cash flow healthy, which matters enormously for a small operation. If cash flow is tight between deposits, it’s worth exploring working capital options from the same partner so you’re never squeezed.
Software and integrations. The best readers plug into inventory, employee scheduling, loyalty, and accounting tools. That turns a payment device into a business dashboard — one login instead of five.
Connectivity and durability. If you sell outdoors or on the road, confirm the reader has strong battery life and cellular backup. A device that dies mid-transaction is worse than no device at all.
Every payment type, no exceptions. Your customers pay in ways that would have looked like science fiction a decade ago — tap-to-pay cards, Apple Pay and Google Pay, and mobile wallets loaded onto a smartwatch. A modern reader should accept all of them, plus chip and swipe, so you never have to say “sorry, we can’t take that.” Turning away a payment method is turning away a customer, and shoppers rarely give a second chance once they’ve been told no at the counter.
Ready to find the perfect credit card reader for your business?
VMS matches you to the right Clover device and a transparent rate in one quick call — most merchants are taking payments within days.
Or call our team: 888-902-6227
Matching a Reader to Your Type of Business
The fastest way to choose is to start with how your customers pay you, not with a spec sheet.
Retail and boutiques. A countertop terminal at the register plus a handheld for line-busting during rushes is the classic combo. Fast checkout keeps queues short and abandoned carts rare — see how the right setup supports retail payment processing day to day.
Restaurants and cafés. Tableside handhelds let servers take payment at the table, split checks in seconds, and turn tables faster. A countertop unit at the host stand or bar handles pickup and to-go orders.
Mobile and service businesses. Contractors, stylists, cleaners, and trainers thrive with a handheld or phone-based reader. Take payment the moment the work is done and stop chasing invoices for weeks.
Pop-ups, markets, and events. Battery life and cellular backup are everything. A rugged mobile reader means a dead Wi-Fi signal never costs you a sale.
The point is simple: buy the reader that matches your rhythm. A restaurant forcing a fixed terminal into a tableside workflow will fight it every shift, and a market vendor lugging a countertop unit is asking for trouble.
A Real-World Look: The Reader That Paid for Itself

Consider a small landscaping crew that spent years mailing paper invoices and waiting three to four weeks to get paid. Cash flow was a constant white-knuckle ride, and a chunk of every month vanished into “I’ll pay you next week” promises that never quite arrived. When the owner finally added a handheld credit card reader for small business jobs, everything changed. Crews started collecting payment on-site the minute the work was done, right there in the customer’s driveway.
Within a single season, the average time to get paid dropped from weeks to the same afternoon. Late payments nearly disappeared, because tapping a card at the truck is a lot easier than digging out a checkbook. The owner even noticed customers spending a bit more on add-on services once paying was frictionless. The device cost a few dollars a month; the improvement to cash flow was worth many times that. That’s the quiet power of the right reader — it doesn’t just accept money, it changes how reliably money reaches you.
Five Questions to Ask Before You Sign
Before you commit to any provider, get straight answers to these five questions. If a salesperson dodges them, keep shopping.
- What is my true, all-in rate? Ask for the effective rate on a real month of sales, not a teaser number. Every markup should be on the table.
- Is there a contract, and what does it cost to leave? Month-to-month with no cancellation fee is the gold standard. Long lock-ins with steep exit penalties are a warning sign.
- How fast will I be funded? Confirm the deposit timeline in writing, and whether next-day or same-day funding is available.
- What happens if the reader breaks? Ask about replacement time, loaner devices, and whether real human support is available on evenings and weekends.
- Can I keep this hardware if I switch processors? Portable, non-proprietary equipment protects your ability to negotiate down the road.
Those five answers tell you more about a provider than any glossy brochure ever will. A partner who answers plainly is a partner worth keeping.
Avoiding the Hidden Costs of the Wrong Reader
Here’s where good owners get burned. The sticker price on a credit card reader for small business is rarely the real price. The expensive part is what comes after.
Watch for long-term contracts with steep early-termination fees. If a provider locks you into three years and charges hundreds to leave, that’s a red flag, not a partnership. Watch for junk fees too — monthly minimums, statement fees, PCI non-compliance charges, and “regulatory” line items that appear out of nowhere. A single sneaky monthly fee is small; a stack of them can quietly erase your margins. To see how these charges pile up and how to fight back, our guide to lowering credit card processing fees is worth a read.
Also beware of proprietary lock-in. Some readers are welded to one processor, so if the rates climb, your only “choice” is to buy new hardware. Flexible, portable hardware protects your leverage to negotiate. And don’t underestimate support. When your reader goes down on a Saturday afternoon, a real human on the phone is worth more than any feature. If you’re weighing providers, the merchant services FAQs answer the questions owners ask most before they switch.
The wrong reader doesn’t announce itself on day one. It shows up three months later as a confusing statement and a sinking feeling. A little diligence now saves a lot of regret later.
The Bottom Line
A credit card reader for small business isn’t a commodity you grab off a shelf — it’s the front door to getting paid. Get the fit right, insist on transparent pricing, and lean on a partner who answers the phone, and that little device becomes one of the best investments you’ll make this year.
That’s exactly what VMS has done for small businesses since 1998: match owners to the right Clover hardware, back it with honest rates and fast funding, and stick around long after the sale. No maze of hidden fees, no three-year traps — just the tools you need to take every payment with confidence. Ready to make it simple? Let’s find your perfect reader.
Have questions about choosing a credit card reader?
Fill out the form below and a VMS payment specialist will contact you shortly.