

It usually starts with a customer holding up their phone. “Can I just Cash App you?” And because you are a reasonable person who likes revenue, you say sure. Money is money, and losing a sale over the payment method feels silly. Fast-forward a few months, and half your Saturday income is landing in an app that was designed for splitting brunch.
Here is the honest truth about using Cash App for business: it is genuinely convenient, right up until the moment it is not. The fees are real, the limits are real, and the IRS absolutely knows the app exists. Whether it belongs in your checkout line depends on what kind of business you are running — and what kind you are trying to build.
In this guide, we will walk through what a Cash App business account actually costs, where it works beautifully, where it quietly holds you back, and how to know when it is time to graduate to payment tools built for the job.
What a Cash App for Business Account Actually Is
Cash App is run by Block, the same company behind Square, and it is enormous — more than 50 million people use the app every month. Some meaningful slice of that crowd shops with you, which is exactly why “do you take Cash App?” keeps coming up at your counter.
A Cash App business account is a different animal from the personal version. You switch your account type to business in the settings (or open a fresh account), and a few things change right away. You get a $cashtag customers can pay directly, plus a payment link and QR code you can text, print, or tape to the register. No awkward phone-number exchange required.
The trade for all that convenience is simple: every payment you receive now carries a processing fee, and your income gets reported to the IRS on a Form 1099-K once you cross the federal threshold. That is not a bug. That is what being a business account means — you are officially a merchant now, just one running on very informal rails.
It helps to know what Cash App is under the hood: a payment aggregator, not a true merchant account. You are one seller inside a giant shared account, which keeps signup instant but gives you far less standing when something goes wrong. We break down that difference in our guide to merchant accounts vs. payment aggregators.
Can You Use Cash App for Business? Fees, Limits, and Taxes

Short answer: yes, you can. Plenty of small sellers do, and for some of them it is the right call. The better question is what it costs you — in fees, in flexibility, and in paperwork.
The fees: 2.75% of everything
Cash App for business pricing is refreshingly simple: a flat 2.75% comes off every payment you receive. No monthly fee, no hardware, no contract. Sell a $200 vintage dresser, keep $194.50. The app also includes standard and instant deposits to your linked bank at no extra charge, which is friendlier than some rivals — Venmo, for example, still takes up to 1.75% for instant transfers, something we covered in our look at Venmo for business.
But flat-rate simplicity has a compounding cost. At $3,000 a month in Cash App sales, you are paying about $82.50 a month for the privilege. At $8,000 a month, it is $220 — over $2,600 a year, gone. That is a nice used espresso machine, every single year, spent on a payment method you adopted because it felt free.
The limits: verification is not optional
New and unverified accounts run into tight sending and receiving caps quickly. Verifying your identity — legal name, date of birth, the usual — lifts the receiving restrictions for business use. Even then, payment apps are famous for freezing first and asking questions later when volume spikes or activity looks unusual to an algorithm.
If a frozen account during your busiest weekend sounds like a nightmare, you are picturing it correctly. It is the same risk pattern we flagged in our piece on Zelle business account scams: app-based money tools offer thin recourse when things go sideways.
The taxes: the 1099-K is not a suggestion
For 2026, the federal 1099-K reporting threshold is back at $20,000 and 200 transactions, after Congress reversed the planned $600 rule. Some states set lower thresholds, so your form may arrive earlier than you expect. The IRS guide to Form 1099-K is worth five minutes of your time.
One thing the threshold does not change: business income is taxable from dollar one, form or no form. A business account on Cash App makes your bookkeeping cleaner precisely because it separates business payments from your cousin paying you back for concert tickets. Use that separation — your accountant will thank you.
Where Cash App Shines for Small Sellers
Let us give the app its due, because there are situations where Cash App for business is legitimately great.
If you sell at weekend markets or pop-ups, it is hard to beat zero hardware and zero setup. If you run a side hustle — lawn care, lash appointments, resale finds — collecting deposits and payments by $cashtag keeps things moving without a single cable. Tips, small invoices, last-minute payments when the card reader battery dies: all solid use cases.
The customer side matters too. Tens of millions of people already have the app open on their phone, so there is nothing to explain and nothing to download. For a business that is small, mobile, and mostly informal, that frictionless “just scan this” moment is real value. If that describes your operation today, enjoy it with our blessing.
Picture a candle maker who does two weekend markets a month and a handful of Instagram orders in between. Her volume is a few hundred dollars a week, her inventory lives in her head, and she is the only person who ever takes a payment. For her, a $cashtag taped to the tent pole is honestly a great system. The 2.75% costs her less per month than a single tank of gas, and she gets paid before the customer walks away. Nothing about that setup is broken.
The catch is that businesses have a habit of growing. And the exact features that make Cash App perfect for a folding-table Saturday become the bottleneck the day you sign a lease.
Outgrowing app-based payments?
VMS sets up real payment processing — tap-to-pay, receipts, reporting, next-day funding — in days, not weeks.
Or call our team: 888-902-6227
The Hidden Limits That Show Up as You Grow
None of these limitations appear on a pricing page. You discover them one busy Saturday at a time.
It is one phone. Your $cashtag lives on your device, logged into your account. Two customers cannot pay at once, and handing employees your personal phone — with your business balance in it — is a management strategy best described as “hopeful.”
Your books are a mystery novel. Cash App tells you money arrived. It does not tell you what sold, which item is your margin hero, what your staff rang up, or how today compared to last Tuesday. A real point-of-sale system answers those questions automatically; an app built for peer-to-peer transfers never will.
No receipts, no tips flow, no extras. There is no itemized receipt for the customer, no tip prompt doing polite work on your behalf, no gift cards, no loyalty program, no EBT acceptance. Each of those is a small revenue leak, and they add up.
Disputes favor the buyer. When a payment gets disputed, you are a small seller inside a giant aggregator, with in-app support and limited seller protections. With a proper merchant account, you have a named processor, a real dispute process, and a human being on the phone.
The optics eventually matter. “Just Cash App me” sounds friendly from a folding table and slightly alarming from an established storefront. Customers read payment setups as a signal of legitimacy, the same way they read a handwritten sign versus a printed menu. A clean countertop terminal that takes every card and every wallet tells people your business plans to be here next year — and that you take their money, and their data, seriously.
The 2.75% never gets better. Flat-rate pricing never rewards your growth. A merchant account opens the door to better effective rates as volume climbs — and with Zero Fee Processing, you can take processing costs off your plate almost entirely and keep the price you actually posted.
When It Is Time for a Real Payment Setup

Here is the decision rule we give owners every week: if app payments are an occasional convenience, keep the side door open. If you have a storefront, staff, or steady daily volume, your main entrance needs merchant-grade rails.
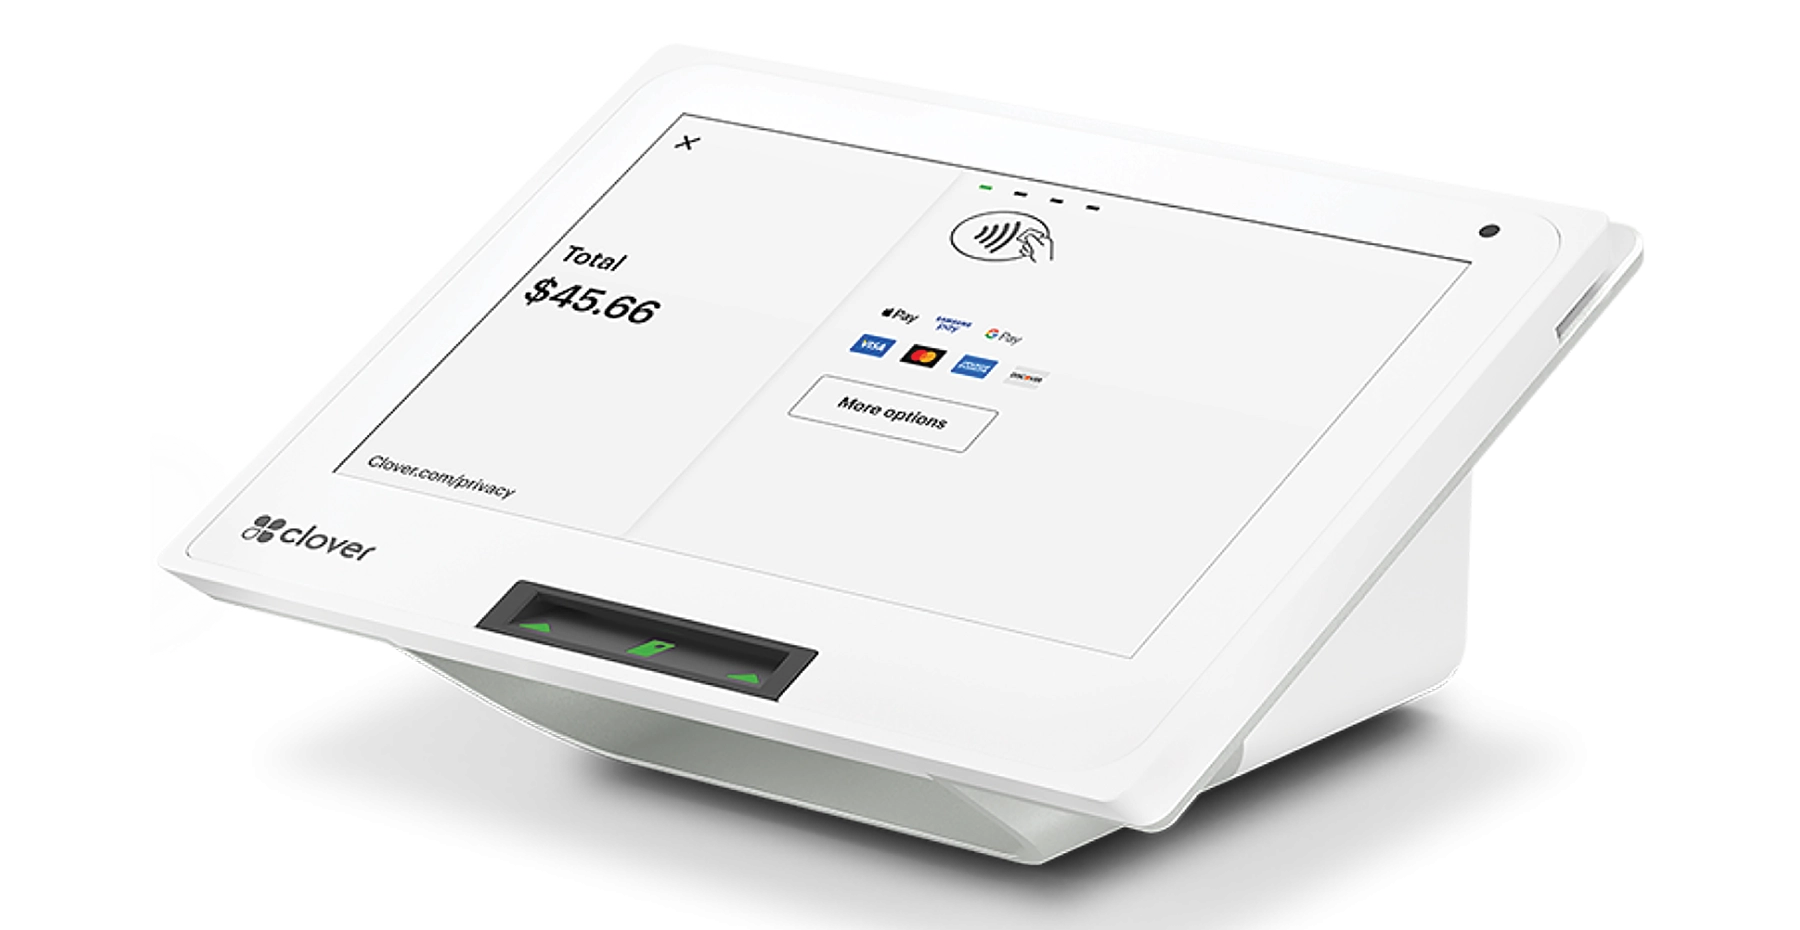
Graduating is less dramatic than it sounds. A Clover Go is a card reader that fits in your pocket and takes tap, dip, and swipe anywhere your phone goes — the same mobility you love about Cash App, with real receipts and reporting behind it. Busier counters step up to a full POS system for small business with inventory, staff logins, and sales reports that actually explain your business to you. We compared the options in our guide to mobile payment processing for small business.
Cash flow gets better too. With next-day funding, yesterday’s card sales are in your bank account tomorrow morning — no instant-transfer games, no waiting on an app’s schedule, no sweating a surprise account review.
And this is where we should mention who “we” are. VMS — Velocity Merchant Services — has been setting up small businesses with payment processing since 1998. Real humans in Downers Grove, Illinois answer the phone, program your equipment before it ships, and stick around after the sale. Customers can keep paying however they like; you finally get the professional setup that grows with you. Have questions first? Our merchant services FAQs cover the ones owners ask most.
Quick Answers Owners Ask About Cash App
Is Cash App safe for business?
Broadly, yes — payments are encrypted, and the business account keeps your commercial income separated from personal transfers. The risk is less about hackers and more about operations: algorithm-driven account freezes, thin seller protections in disputes, and support that lives in an app rather than on a phone line. Safe enough for a side income; thin ice for a payroll-carrying business.
Does Cash App charge fees for business accounts?
Yes. Business accounts pay 2.75% on every payment received, while deposits to your bank — standard or instant — are included. Personal accounts do not pay receiving fees, which is exactly why routing business sales through a personal account is against the rules and a fast way to get flagged.
Can you use Cash App alongside a real POS system?
Absolutely, and plenty of VMS merchants do. The Clover on the counter handles the card, tap, and wallet payments that make up most of the day, while the $cashtag catches the occasional die-hard. Side door open, main entrance professional. What you want to avoid is the reverse: an app doing a POS system’s job.
The Bottom Line on Cash App for Business
Cash App for business is a fine tool and a shaky foundation. Use it for what it is: a fast, familiar way to catch the occasional payment, perfect for markets, side hustles, and getting started. Just do not confuse it with payment infrastructure. The 2.75% skim, the single-phone bottleneck, the silent bookkeeping, and the freeze-first support model all get more expensive as you grow — exactly when you can least afford them.
When you are ready for payments that scale — tap-to-pay speed, itemized receipts, real reporting, next-day funding, and Zero Fee Processing that can eliminate processing costs altogether — VMS will set you up in days, not weeks. Fill out the form below or call 888-902-6227, and a payment specialist who has seen a thousand businesses make this exact leap will map out the right setup for yours.
Have questions about accepting payments beyond Cash App?
Fill out the form below and a VMS payment specialist will contact you shortly.