

Somewhere in your phone right now, there’s a customer who wants to pay you and can’t. Maybe they texted asking if they can put down a deposit. Maybe they saw something in your Instagram story and asked “how do I buy this?” Maybe they owe you for a job you finished last Tuesday, and the check is — as always — in the mail.
Every one of those moments is a sale sitting on the table. And payment links for small business exist to scoop them up. A payment link is exactly what it sounds like: a secure URL you send to a customer — by text, email, DM, or QR code — that opens a checkout page where they pay you on the spot. No website required. No card reader required. No awkward “can you swing by the shop with a card?”
If you’ve ever lost a sale because the paying part was harder than the buying part, this one’s for you. Let’s walk through how payment links work, where they quietly make you money, what they should cost, and how to start sending them this week.
What Are Payment Links for Small Business?
A payment link is a hosted checkout page wrapped in a shareable URL. You create the link — with an amount, a description, and optionally a photo — and send it anywhere a link can go. Your customer taps it, sees what they’re paying for, enters their card (or uses the digital wallet already on their phone), and you get paid. Done.
Think of it as the missing middle between “swipe the card in person” and “build a full online store.” You don’t need a developer. You don’t need a shopping cart. You don’t even need a website. If you can send a text message, you can take a payment.
That flexibility matters more than ever, because your customers have mostly stopped carrying cash. According to Pew Research Center, roughly 41% of Americans don’t use cash for any purchases in a typical week. Your buyers live on their phones — and a payment link meets them exactly where they already are.
How a payment link actually works
You (or your team) create the link from a dashboard, a virtual terminal, or right from a POS app. The link points to a secure, PCI-compliant checkout page hosted by your payment processor — so the sensitive card data never touches your phone, your inbox, or your notebook of doom. The customer pays, you both get a receipt, and the money flows into your account with the rest of your card sales.
One link can be single-use (“$250 deposit for the Hendersons”) or reusable (“$40 monthly co-ed league fee” posted in your Facebook group). That one distinction unlocks a surprising number of ways to get paid.
Payment links vs. invoices vs. text to pay
These three cousins get mixed up constantly, so here’s the thirty-second version. An invoice is a document — it itemizes work, shows terms, and increasingly carries a pay-now link inside it. Text to pay is a delivery channel — a payment request that arrives as an SMS. A payment link is the underlying tool both of them lean on: the shareable checkout itself, which you can also drop anywhere those two can’t reach — a DM, a group chat, a QR code on the counter, a bio link. You don’t have to pick one. Most businesses end up using all three for different moments, ideally from a single provider so the reporting lands in one place.
Where Payment Links Quietly Win You Sales
The magic of payment links isn’t any single feature. It’s the sheer number of small, everyday moments where “here, just tap this” beats every alternative.

Deposits and service work
If you’re a contractor, detailer, photographer, planner, groomer, or anyone else who books work in advance, deposits are your best friend — and chasing them is your least favorite hobby. Text a payment link the moment a customer says yes, and the job is locked in before they’ve put their phone down. Commitment goes up, no-shows go down, and your calendar stops lying to you.
Sales in the DMs
You post a product photo. Someone comments “I need this.” What happens next decides whether you make money. If your answer is “come by the store” or “let me send you an invoice,” a chunk of those buyers evaporate. If your answer is a payment link dropped straight into the conversation, that impulse becomes revenue in about ninety seconds. For businesses selling through Instagram, Facebook, or a group chat, payment links for small business are the closest thing to a cheat code.
Invoice follow-ups that actually get paid
An invoice with a “pay now” link gets settled dramatically faster than one that asks the customer to call in a card number or mail a check, because you’ve removed every step between “I should pay this” and “I paid this.” If you already use online invoicing, payment links are the natural upgrade for nudges and balances due. And for customers who prefer their phone over their inbox, text to pay delivers the same link straight to their messages.
Preorders, events, and fundraisers
Launching a holiday pie preorder? Selling tickets to a tasting night? Collecting team fees? Create one reusable link, post it everywhere, and watch the payments roll in without a single spreadsheet of IOUs. When the event ends, deactivate the link. That’s the whole workflow.
The in-person backup plan
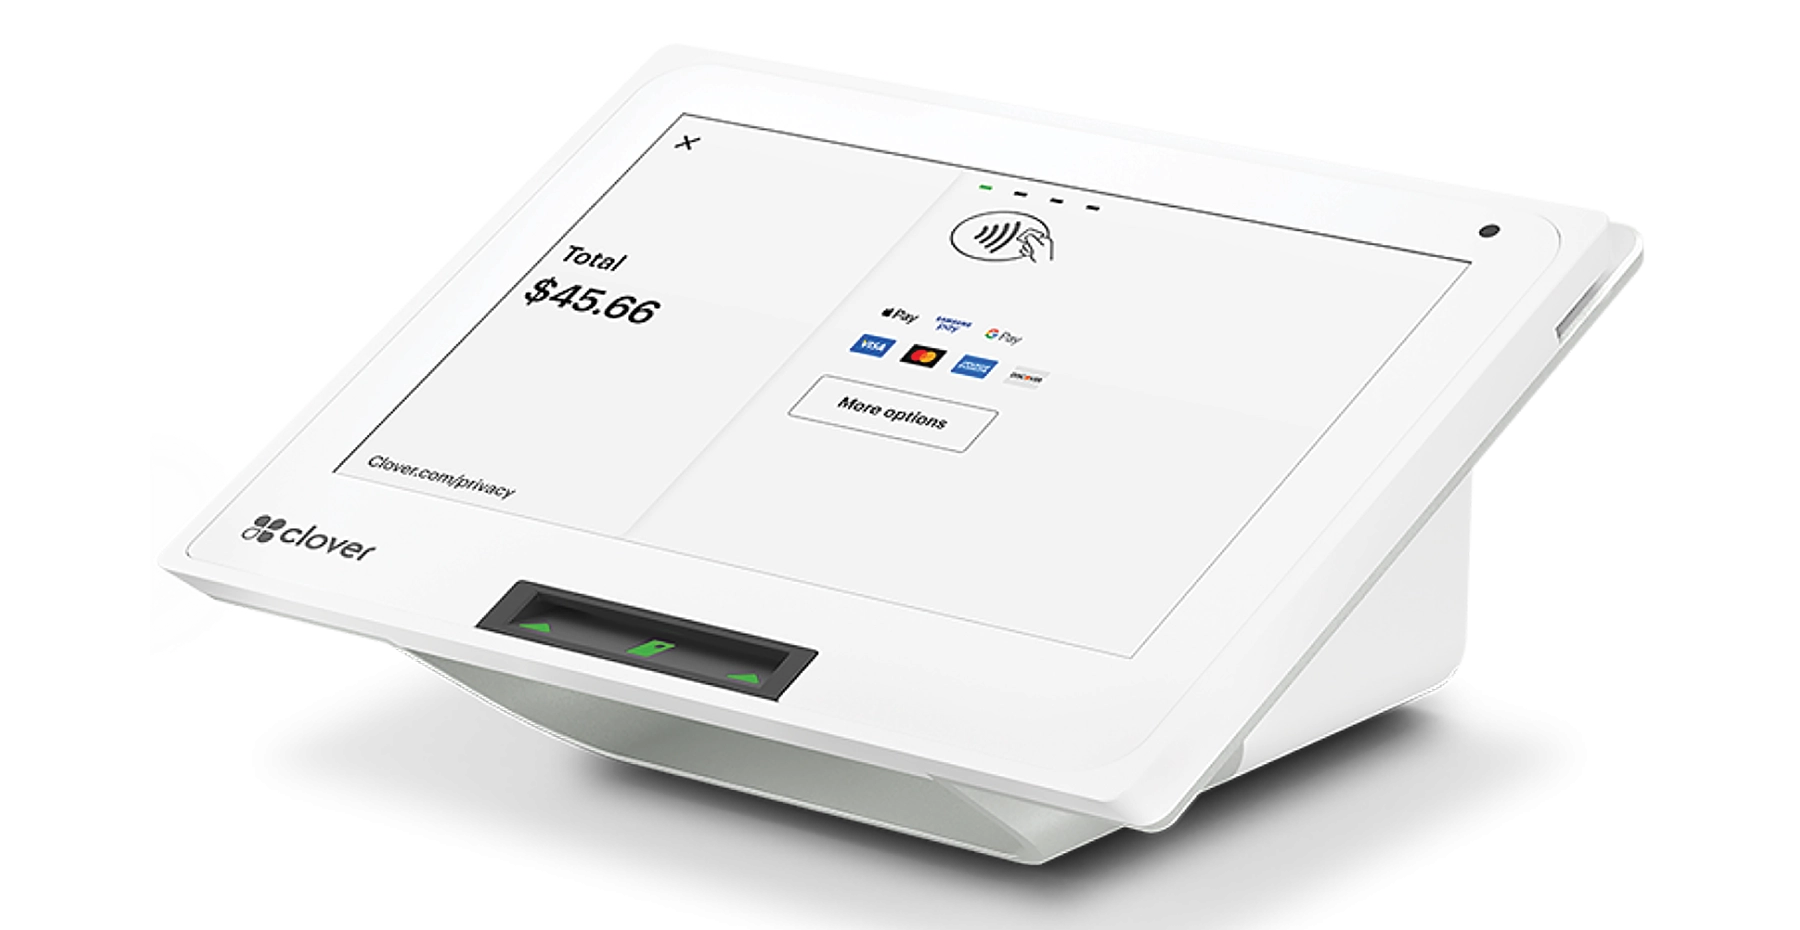
Card reader battery died mid-market? Line at the register three deep and someone just wants to pay and go? A payment link — or its cousin, the QR code taped to your counter — is a checkout lane that never breaks down. Pair it with a Clover Go in your pocket and there is effectively no situation where you can’t take a payment.
What Payment Links Cost (and How to Keep More of Every Sale)
Here’s the part most providers whisper: payment links are card-not-present transactions. Because the card isn’t physically tapped or dipped, they typically process at a slightly higher interchange rate than in-person sales — it’s the same category as online and keyed-in payments.
That’s not a reason to avoid them. A sale you’d otherwise lose entirely is worth infinitely more than the few extra basis points. But it is a reason to pay attention to how your processor prices them.
Watch for three things. First, per-link or “feature” fees — some platforms charge extra just for the privilege of creating links. Second, inflated flat rates — the big DIY platforms love charging 2.9% + 30¢ or more on every linked payment, which quietly compounds into real money. Third, settlement speed — a link is instant, but some providers still make you wait days for the deposit.
This is also exactly where Zero Fee Processing changes the math. With a compliant Zero Fee Processing program, the processing cost is offset at checkout, so the amount on the link is the amount you keep. For a business sending dozens of links a month, that’s the difference between “convenient” and “convenient AND free.”
A quick example of the math
Say you’re a mobile detailer collecting a $100 deposit on every booking, forty bookings a month. On a typical 2.9% + 30¢ platform, those linked deposits cost you about $128 a month — better than $1,500 a year — just in processing. On an interchange-plus plan from a processor that doesn’t mark up card-not-present sales into the stratosphere, that number drops meaningfully. On Zero Fee Processing, it drops to zero. Same links, same customers, same deposits — very different year-end totals.
If you’re not sure what your current setup would charge on a linked payment, that’s a five-minute conversation with a human — the VMS team reads processing statements for fun (someone has to).
Ready to turn every “how do I pay you?” into a done deal?
VMS sets up payment links, Clover POS, and Zero Fee Processing for your business — most merchants are live in days, not weeks.
Or call our team: 888-902-6227
How to Start Sending Payment Links (No Website Required)
The setup is refreshingly boring — in the best way.

Step one: get the right merchant account
Payment links ride on your merchant account, so start there. A modern processor gives you links, a virtual terminal, invoicing, and in-person processing under one roof with one statement. If your current provider treats payment links as a premium add-on, that’s a signal, not a feature.
Step two: pick where you’ll create links
Most owners end up creating links from one of three places: a web dashboard on your laptop, the POS system already on the counter, or an app on your phone. A Clover-based setup does all three — and if you also take orders online, your links live alongside your online ordering in the same reporting view, so end-of-day numbers stay in one place.
Step three: build the habit
The businesses that win with payment links treat them like a reflex, not a feature. Customer hesitates at “how do I pay?” — send a link. Quote accepted — send a link for the deposit. Balance outstanding ten days — resend the link. Repeat customer on a monthly service — convert the link into recurring billing and stop thinking about it entirely.
Write those three or four triggers down, share them with your team, and payment links go from “thing we have” to “reason we get paid faster.”
Keeping Payment Links Safe (For You and Your Customers)
A fair question owners ask: is a link secure enough to trust with card payments? Short answer — yes, when it’s done right, it’s more secure than most of the alternatives you’re using today.
A proper payment link opens a PCI-compliant, encrypted checkout page hosted by the processor. Your customer’s card number never sits in your text thread, your inbox, or on a sticky note by the register — which is precisely how card data should never travel. Tokenization means even the processor’s page doesn’t expose the raw number, and fraud screening runs on every transaction just like it does on your other card-not-present sales.
A few best practices keep everything clean. Send links from a recognizable business number or email, with the customer’s name and what they’re paying for spelled out on the checkout page — trust rises when the page looks like you. Use single-use links for one-off amounts so an old link can’t be reused. Deactivate links for expired offers. And train your team to never, ever take a card number over the phone and type it into a random form when a link would do the same job safely.
Do that, and payment links become one of the most secure ways you accept money — with a paper trail your accountant will actually thank you for.
Get Paid Wherever Your Customers Are
Your customers already buy through their phones. The only question is whether paying you is one tap away or a chore they’ll get to “later” — and every owner knows how often later becomes never.
Payment links for small business close that gap. Deposits get collected the moment a customer commits. DM sales turn into revenue instead of unanswered questions. Invoices stop aging. And with the right processor, none of it costs you a percentage of every sale.
VMS has been setting up small businesses with smarter ways to get paid since 1998 — payment links, virtual terminals, Clover POS systems, and Zero Fee Processing that keeps the whole thing free to run. If you have questions, the merchant services FAQs cover the basics, or fill out the form below and a real human from our Downers Grove team will walk you through exactly what payment links would look like for your business.
The next time someone asks “how do I pay you?” — have a better answer ready.
Have questions about payment links for your business?
Fill out the form below and a VMS payment specialist will contact you shortly.