

It is 4:40 on a Friday afternoon. A transformer down the block blows, the lights go out, the Wi-Fi router blinks off, and the line at your counter is six people deep. Someone asks if you take cash only now. Your newest employee looks at you. Nobody knows where the paper receipt book is, nobody has the landlord’s emergency number, and the last backup of your customer list was made sometime in the spring. A business continuity plan exists for exactly this moment, and the good news is that a smart one fits on a single page.
Most owners hear “business continuity plan” and picture a 90-page binder written by consultants for a bank. A small shop, restaurant or service business needs something shorter: a practical document that answers what has to keep running, who does what, how you keep getting paid, and how you get back to normal fast. This guide walks you through every piece of it, with a plan you can write in one afternoon.
What a Business Continuity Plan Actually Is (and What It Is Not)
A business continuity plan is your playbook for keeping the essential parts of your business running during a disruption, and for restoring everything else quickly afterward. The disruption might be a storm, a fire next door, a burst pipe, a power or internet outage, a cyberattack, a key employee quitting without notice, or a supplier that suddenly cannot deliver.
It is different from a few related documents you may already have:
- Insurance pays you back after a loss. A business continuity plan keeps the loss smaller in the first place.
- An emergency action plan covers life safety: evacuation routes, fire extinguishers, who calls 911. That belongs inside your plan, but it is not the whole thing.
- A disaster recovery plan usually means restoring technology and data. Again, a piece of the puzzle, not the puzzle.
Think of it this way: insurance protects your balance sheet, the emergency plan protects your people, and your business continuity plan protects your revenue and your customers’ trust. For a small business, that last part is usually what decides whether you bounce back or slowly bleed out.
Why Every Small Business Needs a Business Continuity Plan Now
It is tempting to file this under “big company problems.” The numbers say otherwise. According to the U.S. Energy Information Administration, American electricity customers averaged 11 hours of power interruptions in 2024, roughly double the yearly average of the previous decade, with major events such as Hurricanes Beryl, Helene and Milton accounting for 80% of those hours. Eleven hours is an entire business day for most shops.
Natural disasters are hitting small firms more often, too. Researchers at the Federal Reserve Bank of New York found that the share of small businesses reporting losses from a natural disaster doubled from 7% in 2019 to 14% in 2021. And disasters are only one category. Card readers fail, internet providers go down, processors have outages (we wrote about a real one in our breakdown of the FedACH outage that delayed deposits), and people get sick at the worst possible time.
Here is the part that matters most: small businesses rarely fail because of the event itself. They fail because of what happens in the days after. Customers who cannot buy from you on Saturday buy from someone else, and some of them never come back. Payroll comes due whether or not the register was open. A business continuity plan shortens that gap, and the shorter the gap, the smaller the damage.
The One-Page Business Continuity Plan: Six Things It Must Cover
You do not need fancy software. A shared document, a printed copy in the back office and a copy on your phone will do. Work through these six sections and your business continuity plan is mostly written.
1. Your critical functions and how long you can live without them
List the handful of things that make you money or keep you legal: taking orders, taking payments, ordering inventory, running payroll, answering the phone, fulfilling online orders. Next to each, write how long you could survive without it. A coffee shop might survive two hours without its espresso machine but not ten minutes without a way to take cards. A plumbing company might survive a day without its office but not without its dispatch phone. That ranking tells you where to spend your preparation time.
2. Your people and a simple phone tree
Write down who is in charge if you are unreachable, who calls whom, and how you will tell staff whether to come in. Include personal cell numbers, not just work email. Cross-train at least two people on each critical task, which is easier when schedules and roles live in one place; tools like Clover’s employee management features make it simple to see who knows what and to adjust shifts on the fly. If losing staff is your biggest risk, our guide to staying afloat while short-staffed is a good companion read.

3. Your data, records and passwords
Ask yourself: if the back-office computer died tonight, what would you lose? Customer lists, vendor contacts, tax records, recipes, price lists and contracts should all be backed up automatically to the cloud, with a second copy on an external drive kept offsite or in a fire-safe box. Keep a sealed or encrypted record of critical logins, and make sure a trusted second person knows how to reach it. Cloud-based POS systems help here because your sales history, menu and inventory live on the provider’s servers rather than on a single machine in your shop. Security belongs in this section as well; a ransomware attack is a continuity event, so review the basics in our guides to POS security and PCI compliance for small business.
4. How you will keep taking payments
This is the section most small business plans skip, and it is the one that costs the most when it is missing. Write down exactly what happens when your internet is down, when the power is out, and when your card reader or POS fails. We cover the details in the next section, because it deserves its own space.
5. Cash on hand and access to capital
Every business continuity plan needs a money plan. Decide how many weeks of fixed costs (rent, payroll, loan payments, insurance) you want in reserve, and know exactly where that money will come from if revenue stops for a week or two. A rolling 13 week cash flow forecast shows you how long your runway really is. It also pays to line up flexible funding before you need it, because lenders are far less eager after a disaster than before one; VMS working capital options are built for exactly this kind of breathing room.
6. Suppliers, insurance and the building
List backup suppliers for anything you cannot sell without. Keep your insurance policy number, agent’s cell number and claims line in the plan, and read your policy for business interruption coverage before you need it. Add the landlord, utility companies, your internet provider, your payment processor’s support line and a locksmith. In a crisis, the hardest part is often just finding the right phone number.
Keep Selling When the Power or Internet Drops

Payments are where a business continuity plan earns its keep, because every minute you cannot take a card is money walking out the door. Cards and phones now handle the large majority of everyday purchases, so “cash only today” quietly turns away a big share of your sales. Plan for three different failures.
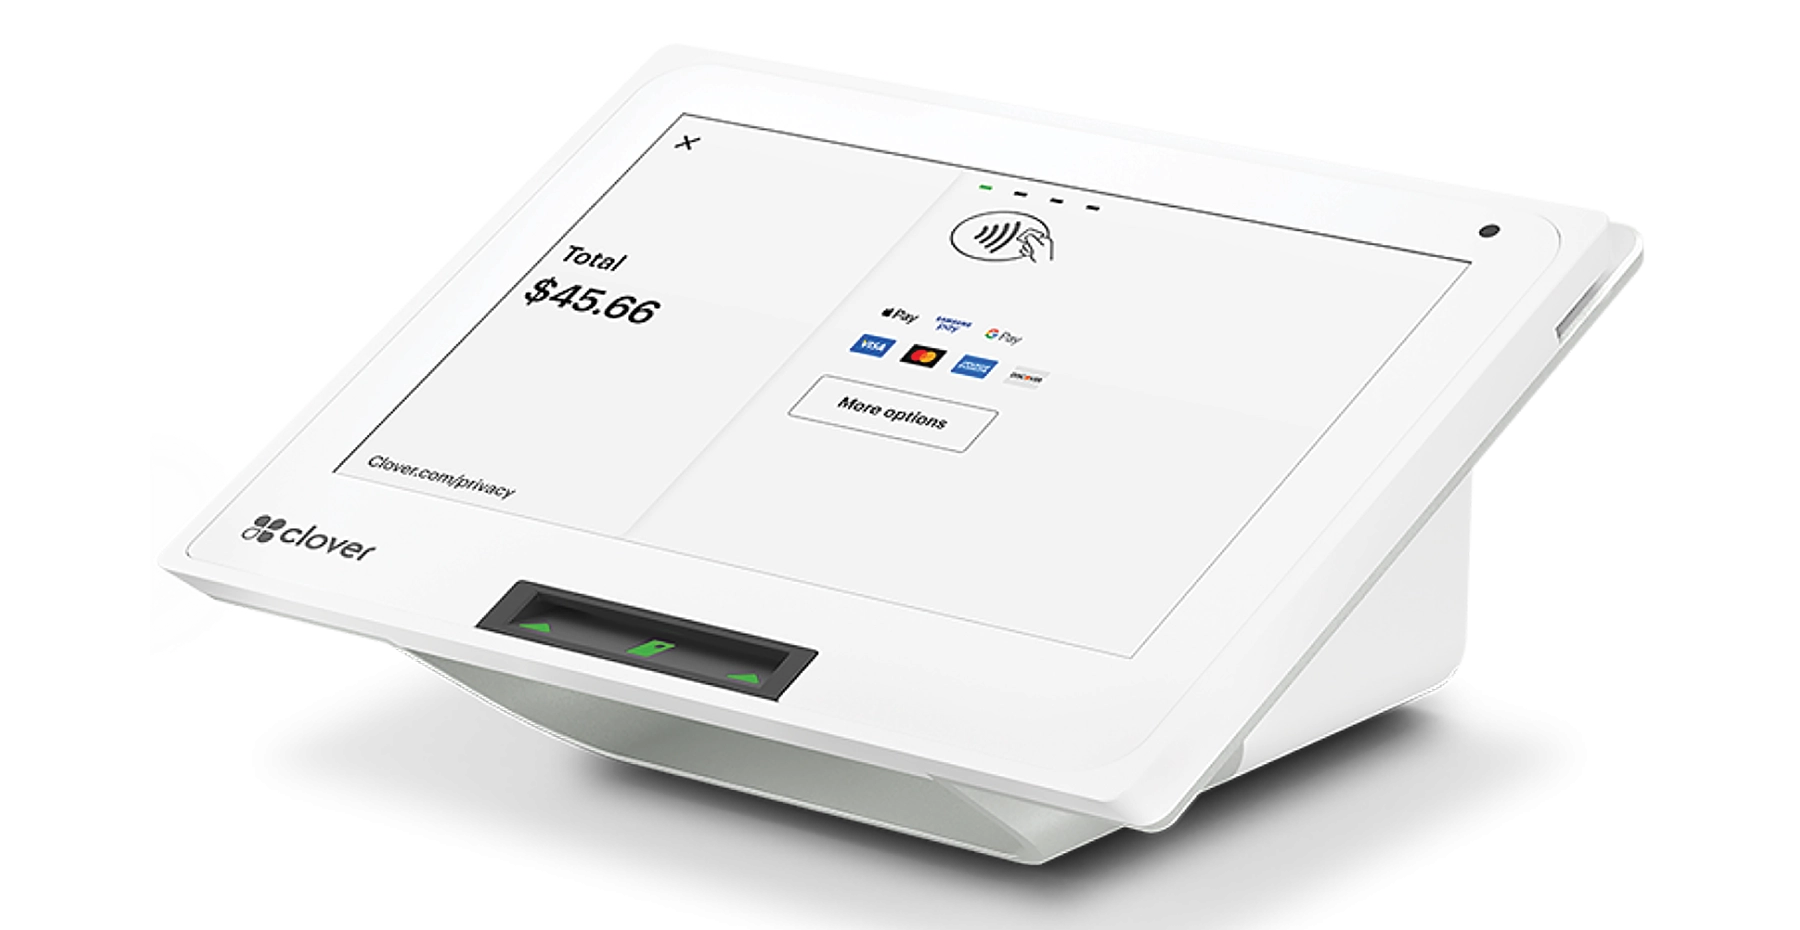
When the internet goes down. Many modern terminals can keep working through a backup connection. Clover devices can switch to a phone hotspot, and some Clover Flex models offer built-in cellular connectivity so the device does not depend on your Wi-Fi at all. Clover also supports an offline payment mode that stores transactions and processes them when the connection returns. Offline payments carry some risk because cards cannot be approved in real time, so set sensible limits in advance. Our explainer on offline credit card processing walks through how it works and what to watch for.
When the power goes out. A countertop terminal plugged into the wall goes dark with the lights. A battery-powered handheld like the Clover Flex or the pocket-size Clover Go keeps working as long as it is charged and has a connection. Keep one charged at all times, keep a small battery bank for your router and phone, and know which outlets (if any) are on a backup circuit.
When the POS or processor itself has a problem. Outages at payment companies are rare but real. Save the support number in your plan, keep a payment link or virtual terminal option ready as a backup path, and read our playbook for what to do when your Clover POS goes down. If you sell online, check that your online ordering can be paused or limited quickly if the kitchen or stockroom cannot fulfill orders.
Finally, write the manual fallback in plain language: where the paper receipt book lives, how to record a sale by hand, and who is allowed to approve exceptions. Rehearse it once. It feels silly until the day it saves a Saturday.
How to Write Your Business Continuity Plan in One Afternoon
Block off three or four hours, grab your manager or a trusted employee, and work through these steps in order.
- Hour one: list your risks. Write down the ten things most likely to shut you down for a day or more. Be specific to your location and industry: flooding, hurricanes, wildfire smoke, a key cook quitting, an internet provider with a spotty record.
- Hour one: rank your critical functions. Use the “how long can we live without it” exercise from section one.
- Hour two: fill in the six sections. Do not aim for perfect. Aim for a phone number, a name and a next step next to each item.
- Hour three: fix the cheapest gaps right away. Turn on automatic cloud backups, charge the spare handheld, print the contact list, and put a copy of the plan in your car and on your phone.
- Last half hour: schedule a test. Put a 30-minute drill on the calendar for next month.
If you want a structured starting point, the federal government’s Ready.gov site breaks business continuity planning into simple stages: prepare, define objectives, identify and prioritize risks, develop strategies, assign teams and tasks, and test. It is free and a helpful checklist to compare against your own draft.
Test Your Plan, Then Keep It Alive
A business continuity plan that sits in a drawer for three years is barely better than none at all. Phone numbers change, staff turn over, and the equipment you depend on gets replaced. Build a light maintenance rhythm into the year:
- Quarterly: run a 30-minute drill. Pull the router plug during a slow hour and take a test sale on the backup connection. Ask a newer employee to find the paper receipt book.
- Twice a year: update the contact list, confirm the backups actually restore, and check that your spare devices are charged and updated.
- Every year: review your insurance, your cash reserve target and your supplier list, and walk through one realistic scenario from start to finish.
- After every real disruption: hold a ten-minute debrief. What worked? What did you wish you had? Add it to the plan that same week.
Seasonal businesses should time their review before the busy stretch, not after it. Our guide for any seasonal business covers how to plan cash and staffing around the calendar, and the same logic applies here: the worst time to discover a gap is the first week of your peak season.
If you are still wondering where to start, look at history. The businesses that came through the last few years in good shape, as we covered in our look back at how businesses should prepare for the next pandemic, were rarely the biggest. They were the ones that had thought through their options before they needed them.
Want payments that keep working when the lights go out?
VMS sets you up with battery-powered Clover devices, backup connectivity and offline payment settings done right — most businesses are ready within days.
Or call our team: 888-902-6227
Your Business Continuity Plan Is a Promise to Your Customers
When something goes wrong, customers remember who stayed open, who answered the phone and who made it easy to keep doing business. A one-page business continuity plan, a charged backup device, a reliable cash cushion and a payment setup that does not fall apart when the Wi-Fi does are what make that possible. None of it is expensive. All of it is cheaper than one lost week.
VMS has helped small businesses accept payments since 1998, and we can help with the payment side of your plan: Clover devices with backup connectivity, offline payment settings configured the right way, flexible working capital, and options like Zero Fee Processing that keep more of every sale in your pocket to build that reserve. Have questions first? Our merchant services FAQs cover the basics, or fill out the form below and a real person will get back to you.
Have questions about business continuity planning for your payments?
Fill out the form below and a VMS payment specialist will contact you shortly.