

There is one moment in every online sale where you either get paid or you do not. It is not the product page, and it is not the shipping estimate. It is the instant a customer has to fish a card out of a wallet and thumb sixteen digits into a phone. Click to Pay was built for that exact moment. It lets a returning shopper check out with a recognized profile instead of retyping card details, and for a small business that difference shows up as real money at the end of the month.
If you sell anything online — a storefront, an invoice link, a deposit for a booking — you have been paying for that friction without ever seeing a bill for it. This guide covers what Click to Pay actually is, what it is not, what the abandonment numbers really say, and how to switch it on without tearing apart a checkout that already works.
What Click to Pay Actually Is (and What It Is Not)
Click to Pay is the card networks’ answer to a problem they all had at the same time: guest checkout is where online sales go to die. It is built on the EMV Secure Remote Commerce specification from EMVCo, the standards body jointly owned by the major networks. Visa, Mastercard, American Express and Discover all implement it, and the specification itself is published on a royalty-free basis. Instead of every merchant building a separate save-my-card system, the network holds the credential and recognizes the shopper wherever they go.
A shopper enrolls in Click to Pay once, usually through their bank or the first time they meet a participating checkout. After that, any store that supports it can recognize them and offer their saved cards. There is no app to download, no new password to invent, and no separate balance to top up.
It helps just as much to be clear about what it is not. Click to Pay is not a payment processor, and it will not change who underwrites your merchant account. It is not a wallet that holds funds. It does not replace your payment gateway — it sits on top of it as a checkout layer, using the same card rails and the same deposits you already have. Your pricing, your funding schedule and your statement all stay exactly where they are.
Your Online Checkout Is Quietly Leaking Sales
Here is the number that should get your attention. Baymard Institute, which maintains a running meta-analysis of fifty separate studies on the subject, puts the average documented online cart abandonment rate at 70.22 percent. Seven out of every ten people who add something to a cart walk away before paying. That figure has barely moved in years, which tells you it is structural rather than seasonal.
The reasons matter more than the headline. Extra costs appearing at checkout drive 47 percent of abandonments, which is a pricing conversation rather than a technology one. But 25 percent abandon because the site wanted them to create an account, and 18 percent because checkout was too long or too complicated. Those last two are precisely the friction Click to Pay was designed to remove, and together they represent a large slice of the orders you are already losing.
Run the arithmetic on your own store. Say you do $18,000 a month online at a $90 average order, which is two hundred orders. If checkout friction costs you even three percent of the shoppers who made it as far as the payment step, that is six orders a month and $540 in revenue. Over a year it is $6,480 — real money for a business your size, and it never shows up as a line item anywhere.
Mobile is where it hurts most. Abandonment on phones runs meaningfully higher than on desktop, and a phone is exactly where typing a long card number, an expiry date and a security code is most miserable. If most of your traffic arrives on a phone, your checkout is being judged by its worst-case experience, and Click to Pay is aimed squarely at that worst case. It is worth reading up on how to speed up the checkout process and the five-second rule for checkout alongside anything you change here.

How Click to Pay Works Behind the Scenes
What the shopper sees
Not much, which is the entire point. A shopper recognized by Click to Pay lands on the payment step and sees their saved cards already listed. They pick one, confirm, and the order is placed. There is no sixteen-digit number to find, no expiry date to squint at, and no security code hiding on the back of a card that is upstairs in a coat pocket. On a good day the whole payment step takes a couple of seconds.
What happens on your side
This is the part worth understanding, because it changes your risk profile. With Click to Pay you generally do not receive the raw card number at all. The framework is specifically designed so that merchants are not left storing and protecting customer payment credentials — you get a network token instead of the actual account number. If you have never dug into how credit card tokenization works, this is the clearest real-world example of it.
That security upgrade also happens to make money, which is rare. Tokenized transactions carry an average uplift of roughly 2.5 percent in payment success rates, largely because a token keeps working when a customer’s card is reissued after a breach or an expiry. Every declined repeat order you quietly stop losing is margin you did not have to sell anything extra to earn.
The networks have also been layering payment passkeys on top — biometric confirmation on the customer’s own device instead of a mailed code or a password. It is worth keeping the two straight. Click to Pay is the checkout layer that removes the typing, and passkeys are the authentication layer that proves the person paying is really the cardholder. Passkey adoption across ecommerce sat near 35 percent in 2026 and is still climbing.
What Click to Pay Means for a Business Like Yours
Strip away the standards-body language and there are four things that actually land on your side of the counter.
- Fewer declines from your best customers. Repeat buyers are the ones most likely to have a card on file that has since been reissued. Token refresh quietly fixes those before you ever hear about them.
- A smaller security surface. If you are not storing card numbers, you have less to lose and less to prove. That does not erase your obligations, but it meaningfully shrinks them.
- A checkout that survives a phone. The gain is largest exactly where abandonment is worst, which is not true of most checkout tweaks.
- No new toll on the transaction itself. The specification is royalty-free, and Click to Pay does not stack a separate network charge on top of your processing.
That last point deserves one honest caveat. While the standard itself adds no network fee, some gateways and shopping-cart platforms do charge for the integration or bundle it into a higher plan. Ask the question directly before you assume it is free. While you are at it, ask what your effective rate actually is — if nobody has walked you through your credit card processing fees lately, that conversation is usually worth more than any checkout button. Businesses that want the cost off their books entirely often pair it with Zero Fee Processing.
Click to Pay vs. Wallets, Payment Links, and Manual Entry
Click to Pay is not competing with everything else you use to get paid. It fills one specific gap, and it helps to see exactly where it sits.
| Way to pay | What the shopper does | Where it shines | What it needs from you |
|---|---|---|---|
| Manual card entry | Types 16 digits, expiry and CVV every time | Nothing — it is the default | The slowest, most abandoned path on mobile |
| Click to Pay | Recognized, picks a saved card, confirms | Repeat online buyers and guest checkout | Gateway support switched on |
| Apple Pay / Google Pay | Taps a phone or confirms with a fingerprint | In person, and in-app checkout | A compatible device and wallet setup |
| Payment links and invoices | Opens a link and pays from anywhere | Phone orders, deposits, custom quotes | Nothing on the customer’s side |
Most small businesses end up running two or three of these at once, and that is completely fine. A retailer might take Click to Pay on the website, a Google Pay tap at the counter, and a payment link for the custom order that came in over the phone. Service businesses lean on online invoicing and a virtual terminal instead. What matters is that all of it lands in one place so your reporting is not scattered across four dashboards.

How to Turn Click to Pay On Without Breaking Your Checkout
The good news is that switching Click to Pay on is usually a configuration change rather than a rebuild. The order of operations matters more than the effort.
- Ask whether you already have it. Many gateways and cart platforms ship Click to Pay support under the Secure Remote Commerce name and simply leave it switched off. Start with a direct question to your provider before you shop for anything new.
- Turn it on in test mode first. Run real cards through a sandbox and watch the whole flow on a phone, not just a desktop browser.
- Put the icon where people can see it. The Click to Pay icon only works if it appears at the payment step without scrolling. Buried below the fold, it may as well not be there.
- Keep guest checkout available. Never force enrollment. The whole point is removing friction, and a mandatory step is friction wearing a new hat.
- Measure the right number. Track completed checkouts as a share of payment-step visits. Clicks on the button tell you nothing on their own.
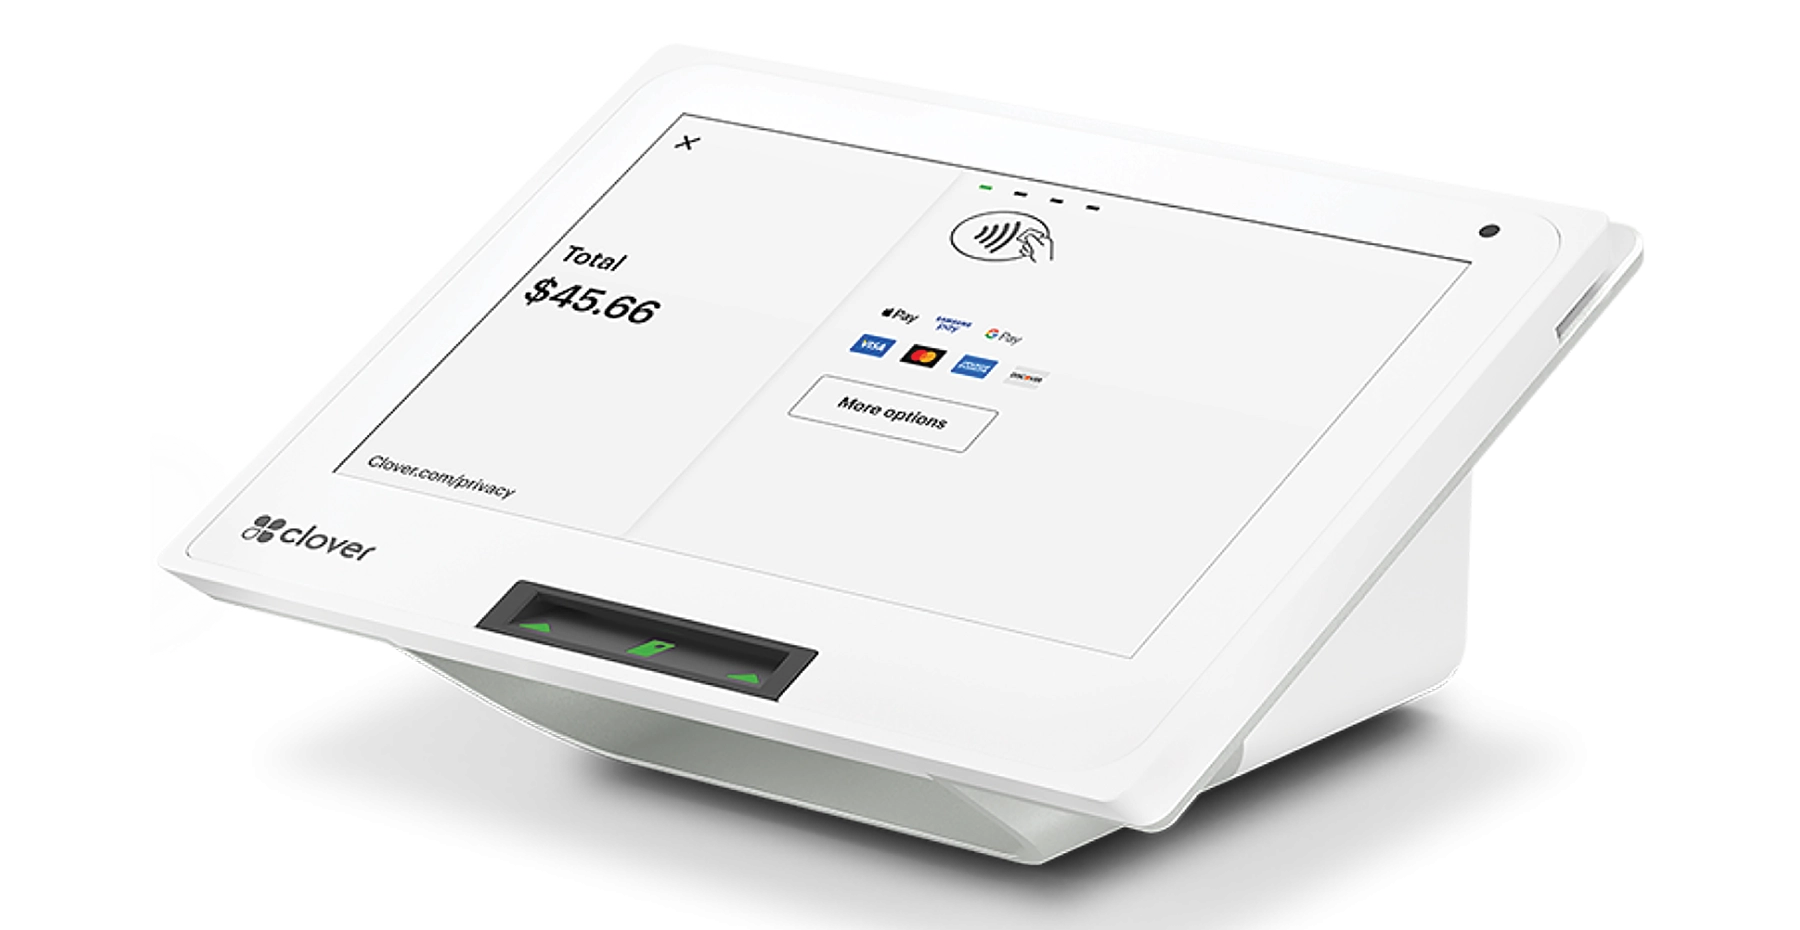
If you sell in person as well as online, this is also the moment to make sure the two halves of your business actually talk to each other. A card tapped on a Clover Mini at the counter and an order paid online should land in the same reporting, which is far easier when your POS hardware and your online ordering run through one provider. Busy retail counters and mobile teams running a Clover Flex get the same benefit.
Once the plumbing is right, the follow-through is a marketing job rather than a technical one. Customers who check out in two seconds are noticeably easier to bring back, so it pairs naturally with loyalty programs and a deliberate approach to customer retention. If you are still deciding how to take money online at all, start with the best ways to accept online payments and work forward from there.
The Honest Limitations
No checkout technology deserves an unqualified sales pitch, and this one has real edges worth knowing before you promise your team a miracle.
- It only helps shoppers who are actually enrolled, and enrollment is still uneven. Your first month will not look like a transformation.
- It does nothing about the 47 percent who leave over shipping and fees. That is a pricing problem, and no button fixes it.
- It is not a fraud cure. Card-not-present fraud still needs the usual controls, and tokenization narrows the target rather than removing it.
- Recognition can miss on a brand-new device or in a private browsing window, so the manual path has to stay clean and usable.
None of that argues against turning it on. It argues against treating it as the only thing you do. Click to Pay removes one specific tax on your revenue, and it removes it permanently, which is more than most checkout experiments can claim. If you want a straight answer about your own setup, the merchant services FAQs cover the common questions and the VMS support team will look at your actual configuration.
Ready to make your online checkout effortless?
VMS sets up Click to Pay, gateways and online ordering for small businesses — usually in days, not months.
Or call our team: 888-902-6227
Making Click to Pay Part of a Checkout That Converts
The businesses that win online are rarely the ones with the cleverest product page. They are the ones who removed a step. Seven in ten carts already end in nothing, a quarter of those shoppers leave over an account they did not want to create, and nearly a fifth leave because checkout asked too much of them. Click to Pay answers both of those objections without asking your customer to learn anything new.
Click to Pay will not fix your shipping table and it will not replace a payment partner who never returns your calls. What it will do is make the last ten seconds of a sale feel effortless, on the device where most of your customers are standing. That is a small change with a compounding return, and it is worth an afternoon of your attention.
VMS has been setting up payment systems for small businesses since 1998, and we will tell you plainly whether Click to Pay is already sitting dormant in your gateway or whether it is worth moving to get it. Either way you get a straight answer about your rates, your hardware and your online checkout — no jargon, no twelve-month runaround.
Have questions about Click to Pay and online checkout?
Fill out the form below and a VMS payment specialist will contact you shortly.